What is USPAP and why does it matter for my appraisal?
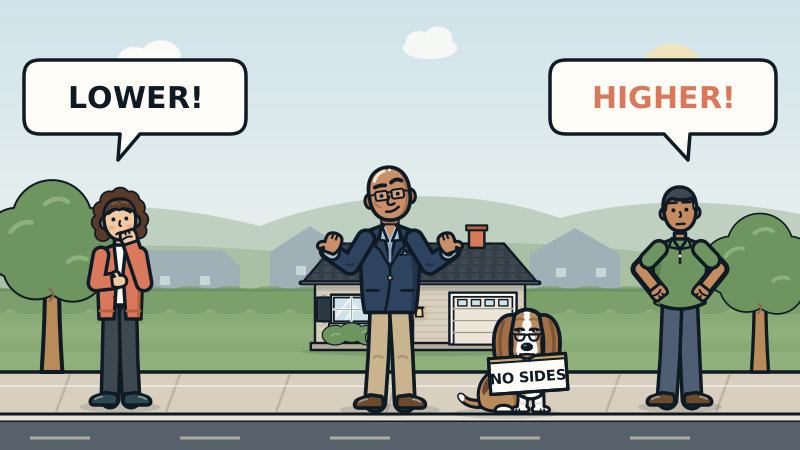
USPAP, the Uniform Standards of Professional Appraisal Practice, is the ethics and performance standard appraisers follow. It is published by The Appraisal Foundation, and Fannie Mae, Freddie Mac, HUD and the VA require USPAP compliant appraisals. It requires appraisers to be independent and impartial, and it limits who the appraiser can share results with.
USPAP is the rulebook appraisers answer to
USPAP stands for the Uniform Standards of Professional Appraisal Practice. Say it out loud once and you will understand why everyone just says "you-spap."
It was developed and copyrighted in 1987 by The Appraisal Foundation, a private, not for profit organization. NAR's explainer traces it to the savings and loan collapse of the 1980s, when trust in banking and the mortgage market had eroded. After that, federal law, the Financial Institutions Reform, Recovery, and Enforcement Act, led the banking regulators to set appraisal standards that at minimum meet USPAP.
Today Fannie Mae, Freddie Mac, HUD and the VA all insist on USPAP compliant appraisals. If a home loan touches any of them, USPAP is in the room.
The standards are written by the Appraisal Standards Board at The Appraisal Foundation. The Foundation says the current edition is the 2024 edition and that USPAP gets a new edition as needed, when the board decides.
One thing USPAP is not: a cookbook. It does not tell an appraiser which comps to pick or what a pool is worth. It sets the standard for how the work is done, not the recipe.
The core rule: the appraiser is on nobody's side
NAR's summary is direct. Appraisers are required to be competent, independent, impartial and objective. They must work without bias, and they may not advocate for the cause or interest of any party or issue.
That last part is the one agents run into. The appraiser is not on the buyer's team, the seller's team or the lender's team. Not even the team that is paying for the order.
USPAP also expects appraisers to follow the laws that apply to their work, including the Fair Housing Act and the Equal Credit Opportunity Act, and to keep improving their skills to stay competent.
For an agent, impartiality cuts both ways. It means the appraiser will not hit your number because you asked nicely. It also means they should not be shading the value down because a lender is nervous. If you have evidence of either, that is a real problem worth raising through the proper channel.
An appraiser who advocates is just an expensive cheerleader with a tape measure.
Who the appraiser can talk to about the results
Confidentiality is where USPAP surprises people most. Appraisers may not disclose confidential information or the results of their appraisal to anyone other than their client, with a few exceptions, plus parties the client specifically authorizes.
Here is the part that trips up buyers and sellers. NAR notes that for most appraisals completed for mortgage lending, the buyer, seller and agents are not the client. The lender is.
That is why the appraiser will happily take your comp packet during the inspection and then go quiet once the report is delivered. They are not being rude. They are following the rule. Questions and corrections after delivery go through the lender.
Private work is different. When a homeowner, an estate, an attorney or an agent hires an appraiser directly for a pre-listing, probate or divorce appraisal, that person or firm is the client. Then the conversation about the results is with them.
Scope of work: who decides how deep the appraiser digs
USPAP's Scope of Work Rule, added in 2006, gives appraisers flexibility over how much to inspect, which data to gather and how much analysis to do. With that flexibility comes the duty to produce credible results.
NAR describes two tests. The scope has to meet or exceed what the intended users would expect for a similar assignment, and what the appraiser's peers would do. And the decision belongs to the appraiser, not the client, the intended user or the borrower.
That is why one appraiser walks the whole lot and another studies sales from the past 60 days while someone else uses six months. USPAP does not hand out one formula. It asks whether the work is credible for the job.
For what it is worth, my view is that credible usually means reading the market in real time, testing the most recent window the data can support, and measuring adjustments from actual sales instead of using rules of thumb. USPAP leaves room for that kind of work. It does not require lazy work, and it does not protect it either.
What USPAP means for you as an agent
- Talk facts during the appraisal. Sharing property details, upgrades and comparable sales is normal. Asking for a value is not.
- Do not expect a phone call after delivery. On a lender appraisal, the client is the lender. Route questions through the loan officer.
- Read the scope of work section. It tells you what the appraiser did and did not do, like interior or exterior only. A lot of disputes end right there.
- Look for reasoning behind the numbers. A credible report explains why the sales were chosen and how the adjustments were supported. If it does not, that is a fair thing to question.
- On private work, ask what you are getting. When you or your client hire the appraiser, you can discuss scope and intended use up front.
- Remember the appraiser's license is on the line. USPAP violations can lead to state discipline. Pushing someone to break it is not a favor to anyone.
USPAP will never be anyone's beach read. But knowing these few rules makes the appraisal less of a black box and makes your conversations with appraisers a lot more productive.
Key takeaways
- USPAP is the ethics and performance standard published by The Appraisal Foundation, first in 1987.
- Fannie Mae, Freddie Mac, HUD and the VA require USPAP compliant appraisals.
- Appraisers must be independent and impartial and may not advocate for any party.
- On most mortgage appraisals, the lender is the client, not the buyer, seller or agents.
- The appraiser, not the client or borrower, decides the scope of work.
People also ask
Is USPAP a law?
USPAP itself is a professional standard from a private nonprofit. It carries legal weight because federal rules, state licensing boards and lenders like Fannie Mae, Freddie Mac, HUD and the VA require appraisers to follow it.
Does USPAP say which comps an appraiser must use?
No. USPAP sets standards for how the work is done and reported. The appraiser decides which sales are most comparable and has to support those choices.
Can an appraiser share the report with the seller?
Only if the client, usually the lender, authorizes it. On most purchase loans the seller is not the client, so the report goes to the lender and the buyer.
Sources
Got a question we haven't answered?
Suggest a topic or ask your own appraisal question. The best ones become posts.