What is the difference between an appraisal and a home inspection?
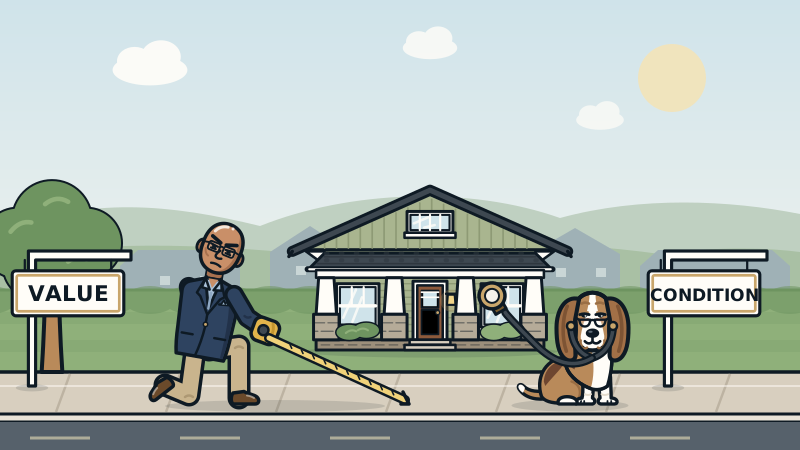
An appraisal estimates the home's market value and mainly protects the lender, which requires and orders it. A home inspection checks the home's physical condition and safety and protects the buyer, who orders it and usually is not required to. An appraisal does not replace an inspection, so most buyers should get both.
One asks what it is worth. The other asks what is wrong.
People mix these two up all the time, and I get it. Both involve a stranger with a clipboard walking through the house you hope to buy. Both produce a report. Both cost a few hundred dollars. That is where the family resemblance ends.
An appraisal is an opinion of market value. I look at the house, then I look at what similar homes nearby actually sold for, and I adjust for the differences. The result is a dollar figure backed by sales, not by how much the seller loves the crown molding.
A home inspection is a check of the home's physical condition and safety. The inspector's whole job is to go looking for trouble: the roof, the plumbing, the wiring, the furnace, the stuff hiding behind the stuff.
Think of it this way. The appraiser tells you whether the price makes sense. The inspector tells you whether the house is going to ruin your weekends.
Who orders each one, who pays, and who it protects
Here is the quick side by side, based on Rocket Mortgage's comparison:
| Appraisal | Home inspection | |
|---|---|---|
| Main question | What is it worth? | What condition is it in? |
| Protects | The lender | The buyer |
| Ordered by | The lender | The buyer |
| Usually paid by | The buyer, often collected by the lender | The buyer |
| Required? | Typically required for a mortgage | Usually optional, unless your contract calls for one |
| Result | A value, with the sales behind it | A list of findings |
The lender cares about value because the house is its collateral. If you stop paying, the bank wants to know it can sell the place and get its money back. It does not much care whether the guest bath fan sounds like a leaf blower. You will care. Every morning.
That is why the inspection is yours. It works for you, it reports to you, and you decide what to do with it.
What I check as an appraiser, and what I don't
When I walk a home, I measure it, count the rooms, photograph the major spaces and rate the overall condition and quality. I note things I can see that affect value or safety, like a stained ceiling or a missing handrail. Then the real work happens at my desk, comparing the house to recent sales.
What I do not do is take the furnace apart, run every faucet for ten minutes or crawl the full length of the attic with a moisture meter. That is not my assignment. Fannie Mae's guide calls for a visual inspection of the accessible areas and says the appraiser is not responsible for hidden conditions. A clean appraisal tells you the price is supported by the market. It does not tell you the sewer line is happy.
This matters even more on FHA loans. Rocket notes that HUD tells FHA buyers, on a form they sign, that an appraisal is not a home inspection. FHA and VA appraisals do check that the home meets the agency's minimum property standards, but meeting a minimum is not the same as having someone look for problems on your behalf.
Facts over feelings works both ways here. A strong appraisal is a fact about the market. It is not a fact about the water heater.
What they cost and when they happen
Rocket Mortgage lists 2026 national averages of $359 for an appraisal and $344 for a home inspection, with most of each falling roughly between $300 and $425. Your price will vary with the size of the house, the area and the loan type. A large, unusual or rural home costs more to appraise because the comparable sales take more digging.
The order usually goes like this:
- Offer accepted. Your contract deadlines start ticking.
- Inspection first. Buyers schedule it fast, because inspection contingency periods tend to be short.
- Appraisal during underwriting. The lender orders it once your loan is moving.
The two can overlap, and sometimes the appraiser and the inspector are in the house on the same day. If you ever see two people with clipboards politely ignoring each other in a hallway, that is just escrow.
What to do: use both reports the right way
- Book the inspection right away. Do not wait for the appraisal. Your inspection window is usually the shorter clock.
- Read the inspection for big-ticket items. Roof, foundation, drainage, electrical and heating are where repair requests make sense. A loose cabinet hinge is not a renegotiation.
- Do not use the inspection to argue value with the appraiser. The appraiser's client is the lender. If you think the appraisal missed something, raise it through your lender.
- Do not use the appraisal to skip the inspection. A value that matches your contract price only says the market supports the price. The contract price does not set value, and value does not certify condition.
- Watch for "subject to repair." If the appraiser finds a safety or soundness issue, the value may depend on a repair being done before closing.
- Paying cash? You may not need an appraisal at all, but you still want an inspection. Some cash buyers get both to check the price.
Key takeaways
- An appraisal estimates market value; an inspection checks condition and safety.
- The lender orders the appraisal. You order the inspection.
- Rocket Mortgage lists 2026 national averages of $359 for an appraisal and $344 for an inspection.
- A good appraisal does not mean a sound house. Get both.
People also ask
Can a home inspection lower my appraisal?
The appraiser works from what they observe and from comparable sales, not from your inspection report. But if the inspection leads to repairs or a new price, the facts of the deal can change.
Does the appraiser get a copy of my inspection report?
Not automatically. The inspection belongs to you. If something in it affects value, talk to your lender about how to share it.
Is an inspection required for an FHA loan?
FHA does not perform home inspections. The FHA appraisal checks minimum property standards, but a full inspection only happens if you arrange it.
Sources
Got a question we haven't answered?
Suggest a topic or ask your own appraisal question. The best ones become posts.