How does an escalation clause work with the appraisal?
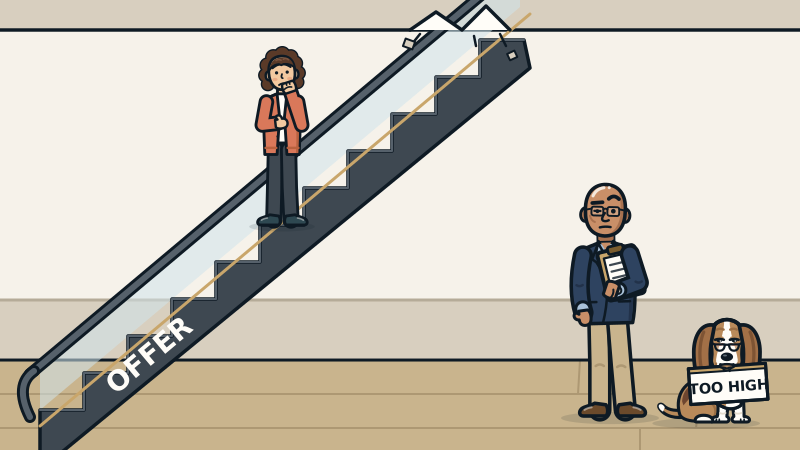
An escalation clause automatically raises a buyer's offer by a set amount above competing offers, up to a stated cap. The appraiser sees the final contract price, but value comes from comparable sales, not from the bidding. If the price escalates past what the market supports, the buyer may need cash to cover the gap.
How an escalation clause works
An escalation clause is a line in an offer that says: if someone else offers more, my offer goes up by a set amount, until it hits a maximum. It keeps a buyer in the running without rewriting the offer every time a new bid shows up.
Here is a made-up example. A buyer offers $800,000 and agrees to beat any competing offer by $5,000, up to $850,000. A competing offer comes in at $830,000. The escalation clause kicks in, and the buyer's price becomes $835,000.
It sounds tidy. The trouble starts when nobody asks the next question: what does the market say the house is worth? An escalation clause measures how badly two buyers want one house. It does not measure what the other houses on the street sold for. Those are two different questions, and only one of them shows up on the appraisal.
What the appraiser actually sees
On a loan sold to Fannie Mae, the lender must make sure the appraiser gets a copy of the complete, ratified sales contract and all addenda. That includes the escalation language and the final price it produced.
The appraiser must say in the report whether the contract was analyzed and what that analysis showed. Any seller-paid concessions get reported too.
What the appraiser does not do is value the bidding war. The contract price does not set value. One buyer and one seller is not the whole market, even if two buyers fought hard over it. Value comes from comparable sales and what similar buyers paid for similar homes.
That does not mean the offers are useless. Multiple offers show demand, and NAR has told agents it is important to share multiple-offer information with appraisers. Strong demand is a reason to look closely at recent pendings and how fast the market is moving. It is not a reason to ignore the comps.
Where the appraisal gap comes from
An escalation clause can widen the gap between the contract price and the appraised value. That is the main risk, and it is the one buyers think about least while they are winning.
For a purchase loan, Fannie Mae bases the loan-to-value ratio on the lower of the sales price or the appraised value. Back to the made-up example: if the price escalated to $835,000 and the home appraises at $810,000, the lender is working from $810,000. The $25,000 difference does not vanish. The buyer covers it in cash, the parties renegotiate, or the deal falls apart, depending on the contract terms.
Some sellers know this. If they expect a gap and doubt the buyer can cover it, they may pass on an escalated offer, even a high one. A big number with no cash behind it is a balloon. It looks great until someone pokes it.
Does a bidding war mean the market moved?
Sometimes, yes. If prices are rising quickly, the comps an appraiser uses may be a month or two behind. In that case, a careful appraiser checks each comp for market change since its contract date and makes a time adjustment backed by evidence. Fannie Mae requires that check.
I read the market in real time for exactly this reason. I look at the most recent window the data supports, at pending sales and at sale-to-list ratios, before I lean on older closed sales.
But a bidding war on one house is not the same as a market that moved. Sometimes one listing just had the right paint color, the right school and two buyers with no Plan B. That is a great day for the seller. It is not proof that every house nearby gained the same amount.
Facts over feelings. If the evidence shows the market caught up to the contract, the appraisal should too. If it does not, the escalation was a bet.
How to use an escalation clause without getting burned
For buyer agents:
- Set the cap with cash in mind. The cap should be the most your buyer can pay including any appraisal gap they might have to cover. Keep the cap within the budget.
- Run comps before you write the cap. If recent sales top out well below the cap, your buyer should know how much of the cap could come out of their pocket.
- Talk to the listing agent first. Ask whether the seller will consider escalation clauses and when offers are due. Some sellers will not accept them.
- Remember the cap shows your hand. An escalation clause tells the seller your buyer's maximum, even if no other offer shows up.
- Look at other terms. A faster close or cleaner terms can sometimes compete without adding price.
- Have the language reviewed. Contract terms and appraisal gap language vary, so have a real estate attorney review anything unusual.
For listing agents and sellers:
- Compare cash, not only price. When you weigh an escalated offer against a lower one, look at the down payment and any appraisal gap language. The highest offer that cannot survive the appraisal is not the best offer.
- Ask how the buyer would cover a gap. Proof of funds beyond the down payment says more than a big cap.
- Price from evidence. A list price built on recent sales makes it less likely the bidding runs far past what an appraiser can support.
Key takeaways
- An escalation clause raises an offer above rival bids, up to a cap.
- The appraiser gets the full contract, but value comes from comparable sales.
- For purchase loans, the loan is based on the lower of price or appraised value.
- Set the cap based on what the buyer can pay in cash if the appraisal comes in short.
People also ask
Does the appraiser know about the escalation clause?
Usually yes. For Fannie Mae loans, the lender must provide the complete sales contract and all addenda to the appraiser.
Can I use an escalation clause with an FHA or VA loan?
It depends on the lender and the contract. Government loans have their own appraisal rules, so ask the loan officer how a gap would be handled before writing the offer.
What is appraisal gap coverage?
It is contract language where the buyer agrees to pay some or all of the difference if the appraisal comes in below the price. It often pairs with an escalation clause in competitive markets.
Sources
- McBrayer: What Real Estate Agents Should Know Before Using an Escalation Clause
- Fannie Mae Selling Guide B4-1.1-05: Disclosure of Information to Appraisers
- Fannie Mae Selling Guide B4-1.3-02: Subject and Contract Sections of the Appraisal Report
- Fannie Mae Selling Guide B2-1.2-01: Loan-to-Value (LTV) Ratios
- NAR: 5 Appraisal Topics Every Agent Should Know
Got a question we haven't answered?
Suggest a topic or ask your own appraisal question. The best ones become posts.