How do appraisal adjustments work?
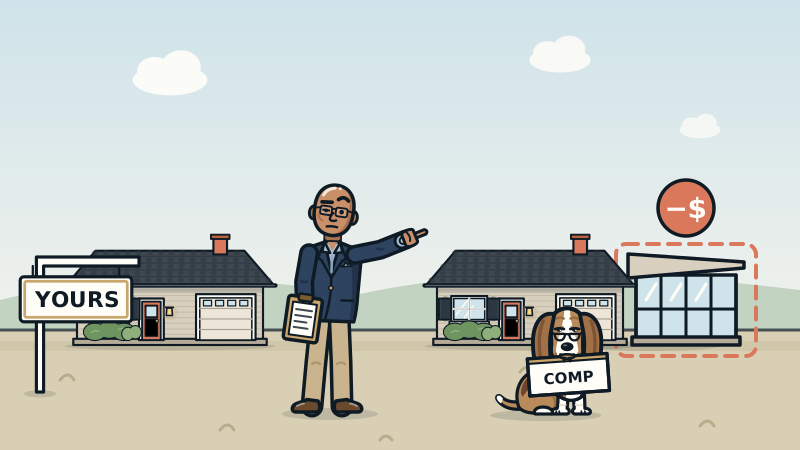
An appraiser adjusts the sale price of each comparable home to make it match yours. If the comp has something better, the appraiser subtracts. If it has something worse, the appraiser adds. Fannie Mae requires those amounts to reflect how the market actually reacts, not a rule of thumb.
Adjustments turn a neighbor's sale into a stand-in for your house
No two houses are twins. Even in a tract where every home came off the same blueprint, one has a remodeled kitchen, one has a pool, and one still has the shag carpet the original owners picked in 1974.
An appraiser starts with recent sales of similar homes nearby, called comparable sales or comps. Then the appraiser asks one question about each comp: what would this house have sold for if it were exactly like yours?
The answer to that question is the adjusted sale price. Do it for several comps, look at where the adjusted prices land, and you have the core of a value opinion.
Notice that the adjustments go on the comp, never on your house. Your house is the fixed point. Everything else gets bent to match it, a little like a family photo where everyone else has to crouch because Uncle Ray refuses to move.
Better comp, subtract. Worse comp, add.
This is the rule people mix up most often, so here it is plainly.
- The comp is better than your house in some way (bigger, newer kitchen, extra bath): the appraiser subtracts from the comp's price.
- The comp is worse than your house in some way (smaller lot, no garage, worn condition): the appraiser adds to the comp's price.
Here is a made-up example. Say the house down the street sold, and it is just like yours except it has one more bathroom. The comp is better, so its price goes down by whatever that bathroom was worth to buyers in that market. Now the comp is a fair stand-in for your house.
Homeowners sometimes see a big minus sign on the report and panic. A minus sign is not a judgment about your home. It just means the comp had something yours does not.
Where the dollar amounts are supposed to come from
This is where the craft is. Fannie Mae's Selling Guide says adjustments must reflect the market's reaction to the difference between the properties. It specifically calls out adjustments based on a rule of thumb when the market data says something else.
Fannie Mae names statistical analysis, modeling and paired sales as ways to support an adjustment. A paired sale is two sales that are alike except for one feature. The difference in price points to what that feature was worth. Cost-based methods, like what it would cost to build or fix a feature, show up in appraisal education too, especially when sales data is thin.
Fannie Mae is also clear that a statement that only says an adjustment was made is not acceptable. And time adjustments, or the decision not to make one, must be supported by evidence.
That is my position too. Adjustments should be measured from real sales, both side by side sales and the wider market. "$20 a foot because that's what we always use" is not a measurement. It is a habit wearing a tie.
The adjustments that surprise people
- Condition often beats age. In the markets I work, buyers react to condition more than to the year built. A remodeled 1960s house can outsell a tired 2005 house, and the grid should show that.
- Seller credits are not dollar for dollar. If a comp's seller paid some of the buyer's costs, the adjustment is whatever the market actually reacted with. Fannie Mae says concession adjustments are negative only, and positive adjustments for concessions are not acceptable.
- Time is an adjustment. If prices moved between a comp's sale date and your appraisal date, the comp gets adjusted for that. Fannie Mae says home price indexes are an acceptable way to support time adjustments.
- Detached space is its own line. A detached ADU or cottage does not get added into the main house's square footage. It is valued separately.
- A broken fixture is not a missing bathroom. It is a condition issue, not a room count issue.
How to read the adjustments on your own report
- Find the sales comparison grid. Your house is in the first column. Each comp gets its own column.
- Check the facts first. Bedrooms, baths, square footage, lot size, garage and condition for your house and each comp. A wrong fact means a wrong adjustment.
- Follow the signs. A minus means the comp was better on that line. A plus means it was worse. If a sign looks backwards, ask about it.
- Look for the support. The report should explain where the big adjustments came from. Paired sales, market data, something. Not a lonely number with no story behind it.
- Compare across comps. The same feature should usually get the same adjustment on every comp, unless the report explains why not.
- Bring evidence, not feelings. If you think an adjustment is off, send sales that show it. That is what a reconsideration of value request is for.
Why a good grid teaches you something
A good appraisal does more than hand over a number. It teaches you how your market prices houses. When the adjustments are measured and explained, you can see what buyers in your neighborhood actually pay for a third bedroom, a bigger lot or a newer kitchen.
That is useful long after the loan closes. It tells you which remodel might pay off, and which one is for your own enjoyment. Both are fine choices. One just has a better return.
When adjustments are guesses, the grid teaches nothing. It is a list of numbers that happen to add up to the contract price. Evidence is what separates an opinion from a wish.
Key takeaways
- Adjustments are made to the comps, never to your house.
- Comp is better, subtract. Comp is worse, add.
- Fannie Mae requires adjustments based on market reaction, not rules of thumb.
- Paired sales and market data are the strongest support for an adjustment.
- Seller concessions are adjusted at market reaction, and only downward.
People also ask
Is there a set dollar amount for a bedroom or a pool?
No. The value of a feature depends on the market and the house. An appraiser should measure it from local sales, not use a national number.
Can an appraiser adjust for a view or a busy street?
Yes. Location differences like views, traffic or backing to a commercial lot can be adjusted, as long as the amount is supported by how buyers in that area react.
Why do some comps have huge adjustments?
Sometimes there simply are not close matches. Large adjustments are not automatically wrong, but they should be well supported.
Sources
Got a question we haven't answered?
Suggest a topic or ask your own appraisal question. The best ones become posts.