What is after repair value (ARV) and how does an appraiser determine it?
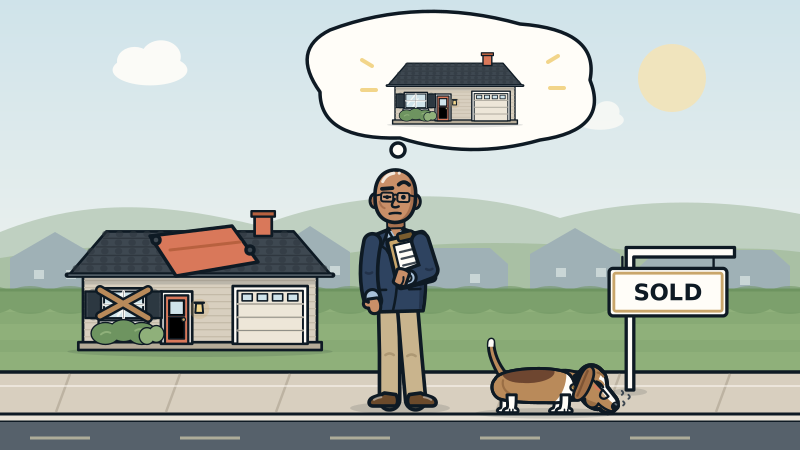
After repair value (ARV) is an estimate of what a property will be worth once the planned rehab is finished. An appraiser determines it by studying the scope of work and comparing the finished house to recent sales of similar, already renovated homes nearby, then adjusting for the differences that buyers actually pay for.
ARV is the value of a house that doesn't exist yet
Lima One, a private lender to investors, describes ARV as an estimate of what the home will be worth once all of the rehab has been completed. It rests on two things: the amount of rehab going into the property, and sales of similar properties in the same neighborhood.
In appraiser terms, ARV is a prospective value. It describes a future version of the house. The federal interagency appraisal guidelines that bank regulators use say that for construction and renovation loans, a lender will generally ask for the current market value as is, plus a prospective value upon completion. Those are two separate opinions about two different houses that happen to share an address.
Every flipper's spreadsheet has a gorgeous house in it. My job is to find out whether the market has ever paid for that house on that street.
When an appraisal includes a prospective value, the same guidelines say there should be a point of reference to the market conditions and time frame the appraiser relied on. In plain words, the report should say which market it is talking about: today's, or the one expected when the paint dries.
How I build an ARV, step by step
- Read the scope of work. Line by line. New roof or a patched one? Full kitchen or new cabinet doors? The finished house is defined by this document, not by the listing photos you hope to take.
- Describe the finished house. Bedrooms, baths, living area, quality of finishes and the condition rating it will have when the work is done. A detached ADU or cottage does not count in the main house's square footage. It gets valued separately.
- Find comparable sales that already look like that. Recently sold, nearby, similar size and similar finished condition. A comp is a comparable sale. For ARV, the best comps are homes that were already renovated when they sold.
- Adjust for the differences, measured from real sales in that market. Buyers react to condition more than age, so a remodeled 1960s house can outsell a tired 2005 one. That has to show up in the numbers, not in a rule of thumb.
- Adjust for time. The guidelines say prospective values should rest on current and reasonably expected market conditions. I test the most recent window the data will support instead of leaning on a lazy 12-month average.
- Reconcile. Weigh the adjusted sales and explain why the value lands where it does.
Where ARV numbers go wrong
Most bad ARVs fail the same few ways.
- The trophy comp. One sale on the block had a view, a bigger lot and a celebrity chef's kitchen. Using it as the yardstick for a standard house is wishful thinking with a spreadsheet.
- The scope doesn't match the value. The budget says paint and carpet. The ARV assumes a full remodel. The appraiser will value the scope, not the dream.
- The neighborhood ceiling. Quartz countertops are nice. They do not move a house into a different ZIP code. Every neighborhood has a top end that buyers will pay, and the sales show where it is.
- List prices instead of sold prices. An asking price is a wish. A closed sale is evidence.
- Square footage that may not count. If the plan adds living area, ask how it will be permitted. Lenders and appraisers look at that.
A rehab budget and a value change are not the same number. Spending $120,000 on a renovation does not guarantee $120,000 of added value. The market decides what it pays for, and the comps tell you what it decided.
How lenders use ARV
ARV matters most to the lender because it caps the loan. Lima One says 70% is the standard maximum percentage of ARV that hard money lenders typically lend, and it shows the loan-to-ARV ratio as simply the loan amount divided by the ARV. On its example, a $175,000 loan on a $250,000 ARV is 70%. That is one lender's description, and every lender sets its own limits.
Regulated lenders also have to look at the as-is value. The interagency guidelines say the lender should understand the property's as-is market value and use the prospective value that matches the credit decision and the phase of the project being funded. Translation: if the project stalls halfway, the lender wants to know what it is holding.
Depending on the loan, the lender may also want proof the work got done. Fannie Mae's HomeStyle renovation program, for example, requires an as-completed value based on the plans and specifications, and a certification of completion on Form 1004D after the work is finished. Private lenders set their own rules, so ask yours what it needs before the first draw.
What to give the appraiser for a stronger ARV
An appraiser can only value the house you describe. The more specific you are, the less guessing happens, and guessing is where values get conservative.
- A line-item scope of work, with quantities
- Finish details: cabinets, counters, flooring, fixtures, windows
- Plans or a floor plan if the layout or size changes
- The contractor's bid and timeline
- Permit status for any added living area or structural work
- Photos of the current condition, including the ugly parts
- Any sales you think are good comps, with addresses. I will verify them, and if they hold up, they go in.
Hand that over and the report can teach you something about your market, which is worth more than a number you have to take on faith.
Key takeaways
- ARV is a prospective value: what the house should be worth once the planned work is done.
- It is built from the scope of work and from sales of homes that were already renovated.
- A rehab budget is not the same as added value. The comps decide what the market pays for.
- Lenders often look at both the as-is value and the ARV, and set their own loan limits.
People also ask
Is ARV the same as an as-completed value?
They describe the same idea: the value once planned work is finished. Lenders and programs use different labels, so read the engagement letter to see exactly what value is being ordered.
Can I use my own comps to support ARV?
You can send them, and a good appraiser will look. They will be used only if they are truly similar and hold up once verified.
Does the appraiser need to see the house for an ARV?
It depends on the lender and the assignment. The order should say whether an inspection of the current condition is required and whether a completion check follows the work.
Sources
- Lima One Capital: What is ARV (After Repair Value)?
- Interagency Appraisal and Evaluation Guidelines (Federal Register, 2010)
- Fannie Mae Selling Guide B5-3.2-03: HomeStyle Renovation Mortgages, Collateral Considerations
- Fannie Mae Selling Guide B5-3.2-05: HomeStyle Renovation Mortgages, Completion Certification
Got a question we haven't answered?
Suggest a topic or ask your own appraisal question. The best ones become posts.